Buying insurance often creates a feeling of security. You pay your premium every year, keep the policy documents somewhere safe, and assume that if something goes wrong, the insurer will take care of it. But insurance doesn’t work quite that simply.
Every insurance policy has conditions, exclusions, limits, deductibles, definitions, and documentation requirements. Understanding these terms before an emergency occurs can save considerable stress later.
1. Understand Exactly What Your Policy Covers
The first question isn’t:
“How much insurance do I have?”
It’s:
“What exactly is insured?”
Two policies with similar premiums can provide significantly different coverage depending on their terms.
Read the policy schedule and the detailed policy wording rather than relying solely on advertisements or verbal explanations.
2. Don’t Ignore Exclusions
Exclusions are circumstances in which the policy doesn’t provide coverage.
They can vary significantly between different types of insurance.
Common examples can include specific types of damage, particular circumstances, policy violations, waiting periods, or conditions that weren’t satisfied.
An exclusion doesn’t necessarily mean the insurer can reject every related claim. The actual wording and circumstances matter.
That’s why reading the precise policy language is important.
3. Check Your Coverage Limits
Insurance doesn’t necessarily mean unlimited reimbursement.
A policy may establish maximum amounts payable for particular categories of loss.
Imagine someone assumes they have comprehensive protection but discovers that a specific category of expense has a much lower limit.
That difference can become financially significant during a major claim.
Why Coverage Limits Matter
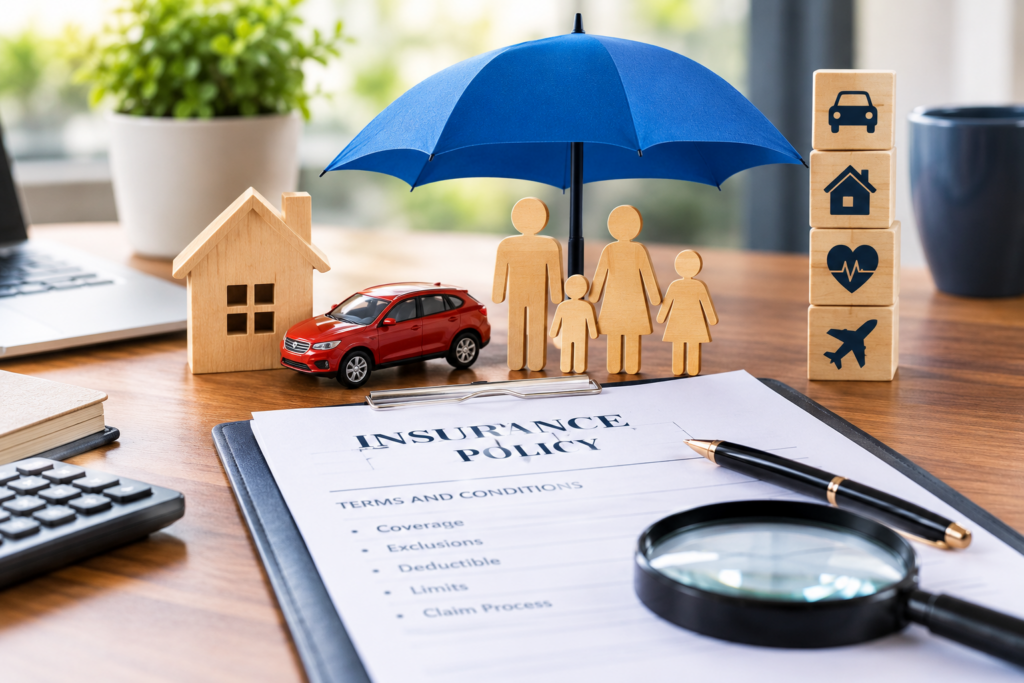
Before buying or renewing insurance, identify:
- Overall coverage
- Category-specific limits
- Deductibles
- Co-payments where applicable
- Sub-limits
- Waiting periods
- Exclusions
Understanding these details can prevent unpleasant surprises.
4. Keep Your Documents Organized
When something goes wrong, searching through hundreds of emails and receipts can become frustrating.
Create a dedicated digital folder containing:
- Policy documents
- Premium receipts
- Renewal notices
- Claims correspondence
- Bills
- Photographs
- Reports
- Repair estimates
Good organization can make the claims process considerably easier.
5. Report the Incident Promptly
Many policies require policyholders to notify the insurer within specified timeframes.
Don’t assume you can wait indefinitely.
If an incident occurs, check the policy’s reporting requirements and notify the insurer as required.
6. Don’t Exaggerate a Claim
Trying to increase a claim by overstating damage or expenses can create serious problems.
Provide accurate information and retain supporting documentation.
A legitimate claim doesn’t become stronger because the numbers are exaggerated.
7. What If the Insurance Company Rejects Your Claim?
A rejected claim isn’t necessarily the end of the process.
Start by asking for the reason for rejection in writing.
Then compare the stated reason with the policy wording.
Depending on the jurisdiction and type of insurance, you may have access to an internal grievance procedure, regulator, ombudsman, arbitration, or court proceedings.
Professional advice may be appropriate for substantial or complicated disputes.
8. Don’t Cancel Important Coverage Just to Save Money
Reducing insurance premiums can appear attractive when household expenses rise.
But saving a relatively small amount today can potentially expose you to a much larger financial loss later.
Instead of automatically choosing the cheapest policy, compare:
Premium + coverage + exclusions + limits + deductibles + claim process.
9. Review Your Policy Every Year
Your circumstances change.
Your income may change. Your property may change. Your vehicle may change. Your family situation may change.
An insurance policy that was appropriate several years ago may no longer match your needs.
Final Thoughts
Insurance is a financial safety net—but only within the boundaries of the contract.
Don’t wait until you are standing in a hospital, repair shop, or financial crisis to discover what your policy actually says.
Mark Delyn focuses on education, learning methods, and academic trends. Her work supports students, educators, and lifelong learners with practical and timely insights.